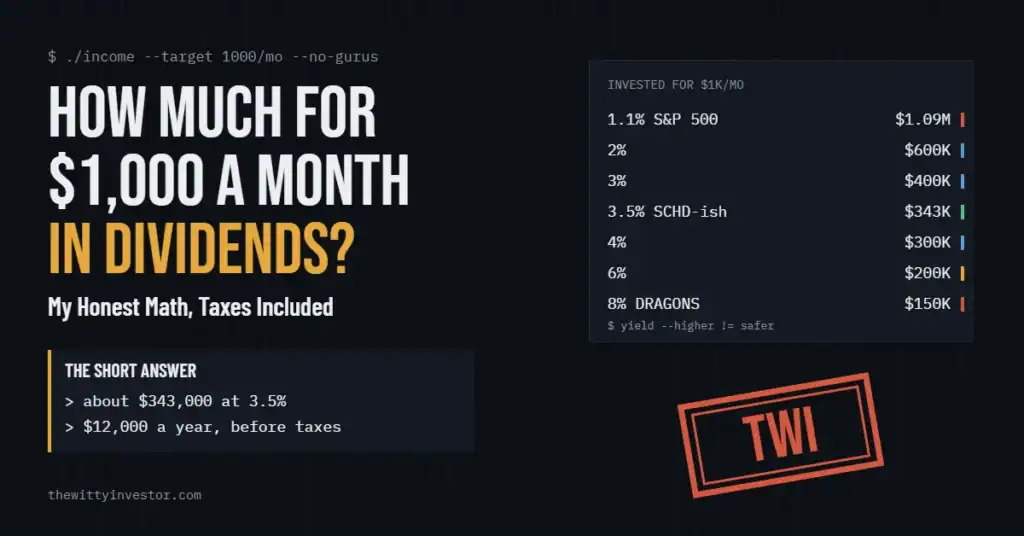
Ask the internet how much money you need to make $1,000 a month in dividends and you will get three answers: $150,000, $300,000 and about $1.1 million. The funny part is that all three are correct. The less funny part is that only one of them is likely to still be paying you in ten years.
I care about this number more than is probably healthy, because $1,000 a month is my goal. Not a hypothetical. Not a thought experiment for a blog post. An actual line in an actual spreadsheet, which lives alongside several other spreadsheets, one of which exists mainly to keep track of the others. I have been a spreadsheet nerd for years, and I have stopped apologizing for it.
I am not there yet. I am getting there slowly, which is the only speed this works at for regular people. So here is the honest math, the parts the “I retired on dividends at 29” crowd tends to skip, and what it actually takes.
This is education, not advice. Yields and prices below were checked in late 2026 and will move. Run your own numbers before you move your own money.
The Short Answer: It Depends Almost Entirely on Yield
$1,000 a month is $12,000 a year. Divide $12,000 by your portfolio’s yield and that is how much you need invested. That is the whole formula. It fits on a sticky note, which is suspicious, because the finance industry has spent decades making it sound like it needs a subscription.
| Average yield | What it looks like | Invested to earn $12,000 a year |
|---|---|---|
| 1.1% | An S&P 500 index fund in 2026 | About $1,090,000 |
| 2% | A dividend-growth fund | $600,000 |
| 3% | A mix of dividend payers | $400,000 |
| 3.5% | A dividend-focused portfolio (SCHD territory) | About $343,000 |
| 4% | A higher-income mix | $300,000 |
| 6% | REIT and high-yield heavy | $200,000 |
| 8% | Here be dragons | $150,000 |
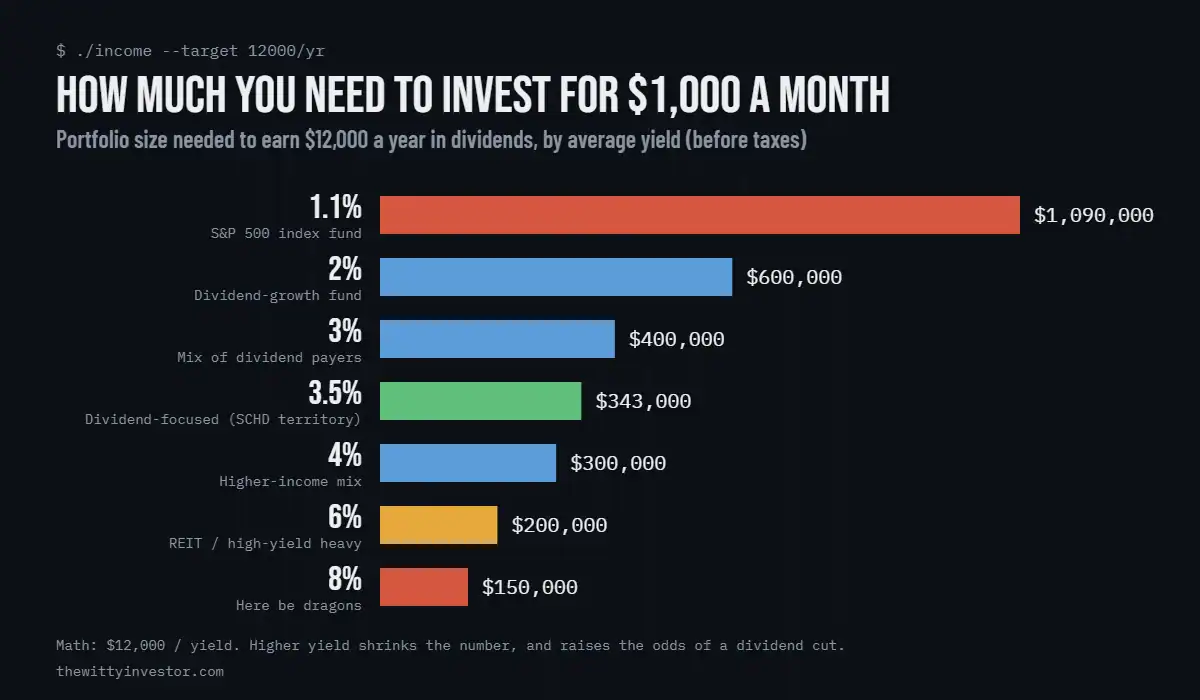
That first row is not a typo. The S&P 500’s dividend yield sank to around 1.2% this spring, near its lowest level in roughly 50 years, because the biggest companies in the index pay little or nothing. Apparently the Magnificent Seven prefer buybacks to sending you a check. Very magnificent. Very stingy.
Dividend-focused funds sit higher. SCHD, the one everybody on Reddit has a tattoo of, has spent most of 2026 yielding somewhere around 3% to 3.5% depending on the week and who you ask. That is why I use 3.5% as my working number. It is high enough to be a real dividend portfolio and low enough that I am not pretending.
Why the 8% Row Is a Trap
Look at that table again. The 8% row says you can get there with half the money. Every fin-fluencer with a ring light has noticed this too.
Here is the problem. A yield is a dividend divided by a price. When the market thinks a dividend is about to get cut, the price drops, and the yield goes up. So a very high yield is often not a gift. It is the market politely clearing its throat. (I wrote a whole post on why most income investors miss the point, and this is chapter one.)
A portfolio built to hit $1,000 a month at 8% can very easily become a portfolio paying $600 a month at 8% on a lot less money. This is fine. Said nobody holding it.
The boring, slightly frustrating truth: the lower-yield path takes more money, but it is the one more likely to still be paying, and growing, when you actually need it.
The Chevron Math (My Favorite Stock to Do Math On)
My first big win on the road to $1,000 a month was Chevron. I set a goal for my CVX position, and I got it there. Nobody threw a parade. My spreadsheet and I had a quiet moment. If you have never felt genuinely proud of a single cell, I cannot explain it to you.
So let’s use it. Chevron pays $1.78 a share every quarter, which is $7.12 a share a year. To get $12,000 a year from Chevron alone, you would need about 1,686 shares. At mid-October 2026 prices, that is somewhere around $380,000 of one oil company.
Which is exactly why you should not do it with one stock. Building your whole income on a single company is like building a house on one very nice brick. Oil prices move. Payout ratios move. Even 30-plus-year dividend raisers can have a bad decade. One position hitting its target is a milestone. It is not a plan. The plan is a lot of those milestones, spread around, adding up.
Hitting that one target did change something for me, though. It is the moment $1,000 a month stopped being a theory and started being arithmetic.
Don’t Forget the Tax Man (He Did Not Forget You)
Here is the part the screenshots of “my passive income this month” leave out. That $1,000 is before taxes.
Most dividends from regular U.S. companies are qualified dividends, which get the same lower rates as long-term capital gains. For 2026, per the IRS inflation adjustments in Rev. Proc. 2025-32:
| Rate | Single filers (taxable income) | Married filing jointly |
|---|---|---|
| 0% | Up to $49,450 | Up to $98,900 |
| 15% | $49,451 to $545,500 | $98,901 to $613,700 |
| 20% | Over $545,500 | Over $613,700 |
If you land in the 15% bracket, your $1,000 a month becomes $850. To actually net $1,000 a month, you need about $14,118 a year in dividends, which at a 3.5% yield means roughly $403,000 invested instead of $343,000. Sixty grand of difference, courtesy of a form. (I read the tax tables so you don’t have to. You’re welcome. And I’m sorry.)
Two more wrinkles. REIT dividends are mostly non-qualified, so they are taxed like regular income. And dividends inside a Roth IRA are not taxed at all, which is the single best argument for doing this inside a retirement account if you can. The IRS dividend rules are worth ten minutes of your life. Also, a high-fee platform quietly does the same damage taxes do, which is why I built a fee drag calculator.
How Long Does It Actually Take?
This is the question everybody really means. Here is the time to reach about $343,000 (the 3.5% number) starting from zero, investing the same amount every month and reinvesting everything:
| Monthly investment | At a 7% total return | At a 3.5% total return | Stuffed in a mattress (0%) |
|---|---|---|---|
| $250 | About 32 years | About 46 years | About 114 years |
| $500 | About 23.5 years | About 32 years | About 57 years |
| $1,000 | About 16 years | About 20 years | About 29 years |
| $1,500 | About 12 years | About 15 years | About 19 years |
| $2,000 | About 10 years | About 12 years | About 14 years |
The 7% column assumes dividends plus price growth, reinvested, which is a reasonable long-run guess and absolutely not a promise. The market does not read my spreadsheets. I have checked.
Two things jump out. First, the amount you put in matters more than which ticker you pick. Going from $500 to $1,000 a month cuts more than seven years off the timeline. No stock-picking skill does that. Second, the mattress column exists to make you feel something. Please feel it.
If you are starting later, the math is less cheerful but not hopeless. I ran those numbers in the real math on starting retirement savings at 45.
How I’m Actually Getting There
No secret system. No course. Just this:
- Track every payment. Mine go into spreadsheets, because of course they do. You can use a dividend tracker app. The point is that you cannot steer toward a number you are not looking at.
- Set targets small enough to hit. $1,000 a month is too big to stare at every day. One position reaching its goal, like my Chevron win, is a number you can actually celebrate this year.
- Favor boring payers. A solid dividend stock or a dividend ETF that grows its payout beats a flashy yield that might vanish.
- Keep costs low. Pick a broker that does not nickel-and-dime dividend investors, and reinvest automatically while you are building.
- Keep a cash buffer. An emergency cash reserve means you never have to sell a dividend payer at a bad time to cover a transmission.
Frequently Asked Questions
How much do I need to invest to make $1,000 a month in dividends?
About $343,000 at a 3.5% average yield, or $300,000 at 4%. Divide $12,000 by your portfolio’s yield to get your own number. If you pay 15% tax on qualified dividends, plan on roughly $403,000 at 3.5% to net $1,000 a month.
Can I make $1,000 a month in dividends with $100,000?
Only with a 12% yield, which is almost always a warning sign rather than an opportunity. With $100,000 at a realistic 3.5%, expect about $290 a month. That is a great start, not a finish line.
What is a safe dividend yield to plan around?
For planning, 3% to 4% across a diversified portfolio is realistic for 2026. Higher yields shrink the amount you need on paper, but they often signal that the market expects a cut.
Are dividends taxed?
Yes, outside retirement accounts. Qualified dividends are taxed at 0%, 15% or 20% depending on your taxable income; for 2026 the 0% rate applies up to $49,450 for single filers and $98,900 for married couples filing jointly. Non-qualified dividends, including most REIT payouts, are taxed as ordinary income.
Should I put all my money in one high-dividend stock?
No. Even a strong long-time dividend payer can cut or freeze its payout. Spread your income across many companies or a fund so one bad year does not cut your income in half.
The Verdict
The honest number for most people is somewhere between $300,000 and $400,000, depending on yield and taxes. Anyone promising a lot less is usually selling a high yield that comes with a trap door, or a course that comes with a monthly fee.
As for me, I am still climbing. One position at a time, one quarterly payment at a time, one spreadsheet cell at a time. It is not glamorous, and nobody is going to make a reel about it. But it is real, and it adds up. I will let you know when I get there. Assume a very large, very colorful spreadsheet will be involved.
Want the next one in your inbox? The Verdict newsletter sends one honest take a week. No hype, no ring light.